The Silent Compounding of Tax Neglect: What a Single Year of Poor Planning Actually Costs You Over a Decade
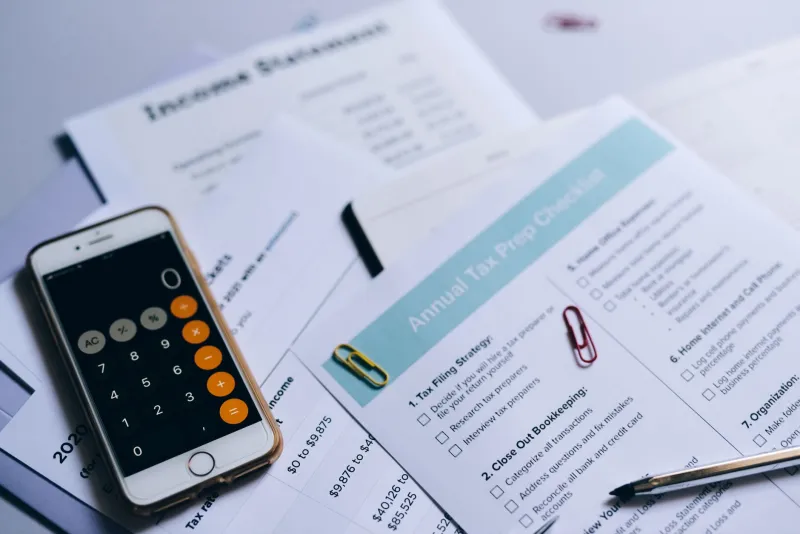
There is a version of wealth-building that most people never encounter. It does not appear in motivational content about hustle, nor does it dominate conversations about investment returns. It lives, quietly and consequentially, inside the architecture of your tax strategy—or the absence of one.
The uncomfortable truth is this: the difference between a wealth builder who earns $200,000 per year and keeps $145,000 of it, and one who earns the same amount and keeps $115,000, is not a matter of discipline or market timing. It is a matter of structure. And over ten years, that $30,000 annual gap—compounded at a modest 8% annual return—does not produce a $300,000 difference. It produces a gap exceeding $520,000 in real, investable wealth.
That is the compound tax: not a line item on your return, but the cumulative, decade-long cost of failing to treat your tax strategy as a wealth instrument from the very beginning.
Why Year One Is the Hinge Point
Most people approach taxes reactively. They earn income, they spend, they invest what remains, and then—somewhere between January and April of the following year—they learn what they owe. This sequence feels natural. It is also financially catastrophic over time.
The decisions that carry the greatest long-term weight are rarely made at tax time. They are made in the months before meaningful income begins to flow: the choice of business entity, the selection of retirement account structures, the timing of income recognition, and the identification of deductible business activity. These are architectural decisions, and like the foundation of a building, they are extraordinarily difficult and expensive to alter once construction is underway.
Consider a straightforward scenario. An independent consultant begins generating $150,000 per year in self-employment income. Operating as a sole proprietor, she pays self-employment tax of 15.3% on her net earnings—roughly $21,000—before federal income tax is even calculated. Had she instead elected S-corporation status, designated a reasonable salary of $80,000, and taken the remaining $70,000 as a distribution, her self-employment tax exposure would have dropped to approximately $11,000. That is a $10,000 annual difference, achieved through a single structural decision made before her first invoice was sent.
Over ten years, with that $10,000 annual savings invested at 8%, the compounded value exceeds $156,000. This is not a tax loophole. It is standard tax planning—the kind that every informed wealth builder should be executing in year one.
The Deduction Architecture Most Earners Never Build
Beyond entity structure, the second major failure in early-stage tax planning is the absence of a deliberate deduction strategy. The US tax code offers a substantial—and frequently underutilized—array of deductions for individuals who are self-employed, operating a business, or generating income outside traditional employment.
Health insurance premiums, home office expenses, retirement contributions, business vehicle use, professional development, and software subscriptions are among the categories that, when properly documented and claimed, can meaningfully reduce taxable income. Yet the majority of early-stage earners either claim too little out of unfamiliarity or claim incorrectly out of overconfidence—both of which carry long-term costs.
The SEP-IRA and Solo 401(k) represent particularly powerful instruments. A self-employed individual can contribute up to 25% of net self-employment income to a SEP-IRA, with a 2024 limit of $69,000. A Solo 401(k) allows both employee and employer contributions, with combined limits reaching the same ceiling. At a $50,000 annual contribution, the immediate tax deferral for someone in the 24% federal bracket is $12,000 per year—and the deferred amount continues compounding inside a tax-advantaged account rather than being surrendered to current-year taxation.
Building this deduction architecture in year one is not merely about reducing this year's bill. It is about establishing a repeatable system that compounds its advantages annually.
Timing as a Wealth Strategy
Income timing is one of the most underappreciated levers in a sophisticated tax strategy. The US tax system is structured around calendar-year income recognition, and within that structure, considerable flexibility exists—particularly for business owners and self-employed professionals.
If you anticipate that your income will be substantially higher next year than this year, accelerating deductible expenses into the current year and deferring income where possible can reduce your effective tax rate in both periods. Conversely, if your income is unusually elevated in a given year due to a large contract or asset sale, bunching charitable contributions, prepaying business expenses, or maximizing retirement contributions can prevent a one-time income spike from permanently distorting your tax picture.
For investors, the principle of tax-loss harvesting—strategically realizing capital losses to offset gains—adds another dimension. A portfolio managed with no attention to tax efficiency will, over a decade, surrender a meaningfully larger share of its returns to the IRS than one managed with basic harvesting discipline. Studies suggest the annual benefit of systematic tax-loss harvesting ranges from 0.5% to 1.5% of portfolio value—a figure that, on a $500,000 portfolio, represents $2,500 to $7,500 per year in preserved returns.
The Professional Relationship Most Wealth Builders Underinvest In
A recurring pattern among early-stage wealth builders is the tendency to view a CPA as a once-per-year expense rather than a strategic partner. This framing is costly.
A qualified tax professional—specifically one who works with business owners and self-employed individuals, rather than simply processing W-2 returns—is among the highest-return relationships a wealth builder can maintain. The annual fee for proactive tax advisory work typically ranges from $2,000 to $6,000 for a mid-level earner. Against the $10,000 to $30,000 in annual tax savings that strategic planning routinely produces, this represents a 5x to 10x return on investment before compounding is considered.
The key distinction is proactive versus reactive engagement. A reactive CPA tells you what you owe in April. A proactive tax strategist reviews your income trajectory in October, identifies opportunities before the year closes, and builds a multi-year plan that accounts for your business structure, investment activity, and projected income growth.
If your current tax professional does not contact you before December with planning recommendations, you are almost certainly leaving money on the table.
What the Ten-Year Ledger Actually Looks Like
Returning to the foundational premise: a $50,000 annual difference in after-tax income, compounded at 8% over ten years, produces a wealth gap of more than $780,000. Even a more conservative $20,000 annual difference—entirely achievable through entity optimization, retirement contributions, and basic deduction discipline—compounds to over $310,000 over the same period.
These are not abstract projections. They represent the real-world divergence between two wealth builders who earned identical gross incomes but made different structural decisions in year one.
The compound tax is silent precisely because it does not appear as a line item anywhere. It manifests only in the gap between what your portfolio could have been and what it actually is—a gap that widens every year you delay.
The most effective time to build your tax architecture was the year you began earning seriously. The second most effective time is now.