Your Calendar Doesn't Lie: How to Read Your Schedule as a Wealth-Building Document
The Financial Document No One Checks
There is a version of your financial life that lives inside your bank account. You probably review it regularly—sometimes obsessively. You know your monthly subscriptions, your grocery spend, maybe even your average daily coffee cost down to the cent.
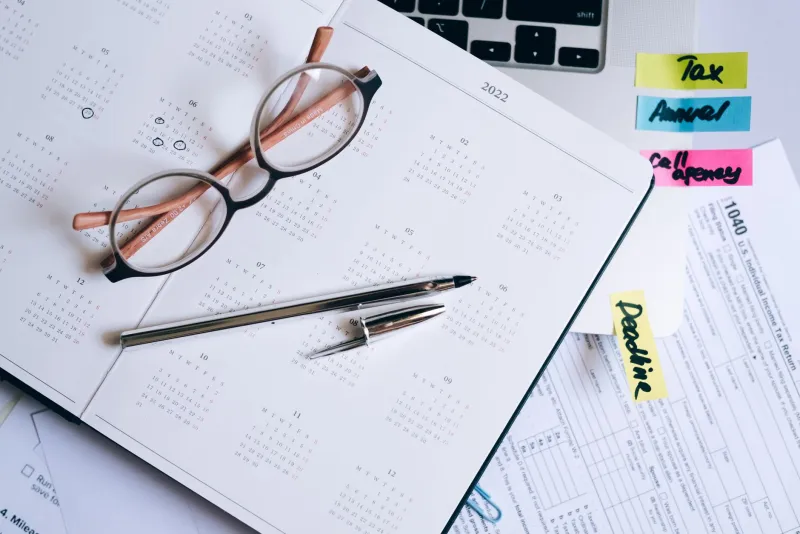
And yet the document that most accurately predicts your financial future is sitting in your phone or laptop, largely unexamined. It is your calendar.
Time is the upstream input. Every dollar you have ever earned began as an hour you chose to spend in a particular way. Every wealth gap between you and someone who started at the same income level can, in large part, be traced back to a divergence in how the two of you allocated time over months and years. That is not a philosophical observation—it is a mechanical one. Understanding it changes how you approach both your schedule and your finances.
Why High Earners Still Hit Plateaus
One of the more disorienting experiences in personal finance is reaching a salary or revenue level you once considered aspirational—and then discovering that your net worth has not moved proportionally. The income went up. The wealth did not follow.
This disconnect almost always has a time dimension. As income increases, obligations tend to multiply at a similar rate. More meetings. More social commitments that feel professional. More administrative friction that seems unavoidable. The calendar fills, and the hours that once went toward skill-building, high-leverage projects, or income diversification quietly disappear beneath layers of busyness that feel productive but function as wealth-neutral at best.
Wealth-neutral time is not wasted time in the traditional sense. It is time that keeps the machine running without advancing it. Responding to routine emails, attending status-update meetings, managing logistics that could be delegated—these activities are often necessary, but they consume hours that could otherwise compound toward something larger.
The plateau is not caused by laziness. It is caused by a calendar that was never deliberately designed for wealth acceleration.
Conducting the Audit: A Practical Framework
The goal of a calendar audit is not to eliminate all obligations or pursue some maximalist vision of productivity. It is to achieve clarity about where your hours are actually going—and whether that distribution reflects your stated financial priorities.
Start by pulling three to four weeks of calendar data. If you do not use a digital calendar consistently, reconstruct your typical week on paper as honestly as you can. Include everything: work blocks, commutes, recurring calls, social engagements, errands, and the unscheduled hours that tend to get absorbed by low-effort scrolling or unfocused task-switching.
Then sort every recurring time block into one of three categories.
Wealth-amplifying time generates income, builds a skill with direct market value, expands a network with tangible professional implications, or advances a project with equity or revenue upside. Client work, high-stakes negotiations, learning that increases your rate or salary, building a business asset—these belong here.
Wealth-neutral time maintains your current position without meaningfully advancing it. Routine administrative tasks, most internal meetings, social obligations with no professional dimension, and maintenance activities fall into this category. These are not inherently bad. They are simply not the engine.
Wealth-draining time actively competes with wealth-building without offering proportional return. This includes commitments you accepted out of guilt or social pressure, low-value projects you have not yet had the discipline to exit, and the diffuse hours lost to decision fatigue and context-switching between unrelated tasks.
Once categorized, calculate the rough percentage of your waking hours that each category represents. Most people find the distribution genuinely surprising.
The Disguised Obligation Problem
One of the more insidious findings of a calendar audit is the obligation that has disguised itself as necessity. In American professional culture particularly, availability is often mistaken for diligence. Responding to every message immediately, attending every optional meeting, saying yes to every reasonable request from a colleague or client—these behaviors feel responsible. They are often financially costly.
Every hour spent in reactive mode is an hour unavailable for the deliberate, focused work that actually moves income upward. Research on deep work consistently shows that the highest-value cognitive output—the kind that commands premium compensation—requires uninterrupted blocks of time that most calendars simply do not protect.
If your audit reveals that your schedule is primarily reactive—structured around other people's requests rather than your own strategic priorities—you have identified a significant constraint on your earning trajectory. The fix is not working more hours. It is restructuring which hours you make available to others and which you protect for compounding work.
The Time-to-Money Conversion Rate
A useful lens for evaluating any time commitment is what might be called your personal time-to-money conversion rate. This is not simply your hourly wage. It is the effective dollar value generated per hour across all your activities when measured against your actual financial outcomes.
Consider two professionals earning identical salaries. One spends eight hours each week on activities that are building a consulting practice on the side—developing expertise, cultivating relationships, producing content that attracts clients. The other spends those same eight hours on low-urgency work tasks and passive entertainment. Five years later, their net worth divergence will be dramatic, and it will trace directly back to that weekly eight-hour difference in time allocation.
You can raise your time-to-money conversion rate without working additional hours. The mechanism is substitution: replacing lower-yield time blocks with higher-yield ones. Delegation, automation, and the discipline to decline non-essential commitments are the practical tools for achieving that substitution.
Redesigning the Calendar With Intention
Once the audit is complete and the categories are clear, the next step is deliberate redesign. This does not require a dramatic overhaul. Incremental shifts compound meaningfully over time.
Identify two to three recurring time blocks that currently fall into the wealth-neutral or wealth-draining category. Examine whether each is truly non-negotiable. For those that are, look for ways to compress or streamline them. For those that are not, begin the process of reducing or eliminating them.
Next, create protected blocks specifically designated for wealth-amplifying activity. Treat these with the same commitment you would apply to a meeting with a major client. They are not flexible. They are the appointments you keep with your own financial future.
Finally, build a quarterly review into your schedule—a recurring appointment where you repeat the audit process and assess whether your calendar distribution has drifted back toward reactive busyness. It almost always does, absent active attention.
The Honest Reckoning
Your calendar is a record of your revealed priorities—not the priorities you describe in conversation or intend in the abstract, but the ones you have actually acted on with the finite hours available to you. That is what makes it more honest than a budget, more telling than a goal list, and more predictive than an income statement.
Wealth building, at its core, is a time allocation problem before it is a money problem. The Americans who build durable financial independence are not necessarily those with the highest incomes or the most sophisticated investment strategies. They are the ones who figured out, earlier than most, that the calendar was the real financial document—and designed it accordingly.